Your Lender for Life
You can buy this home.
I'll show you how.
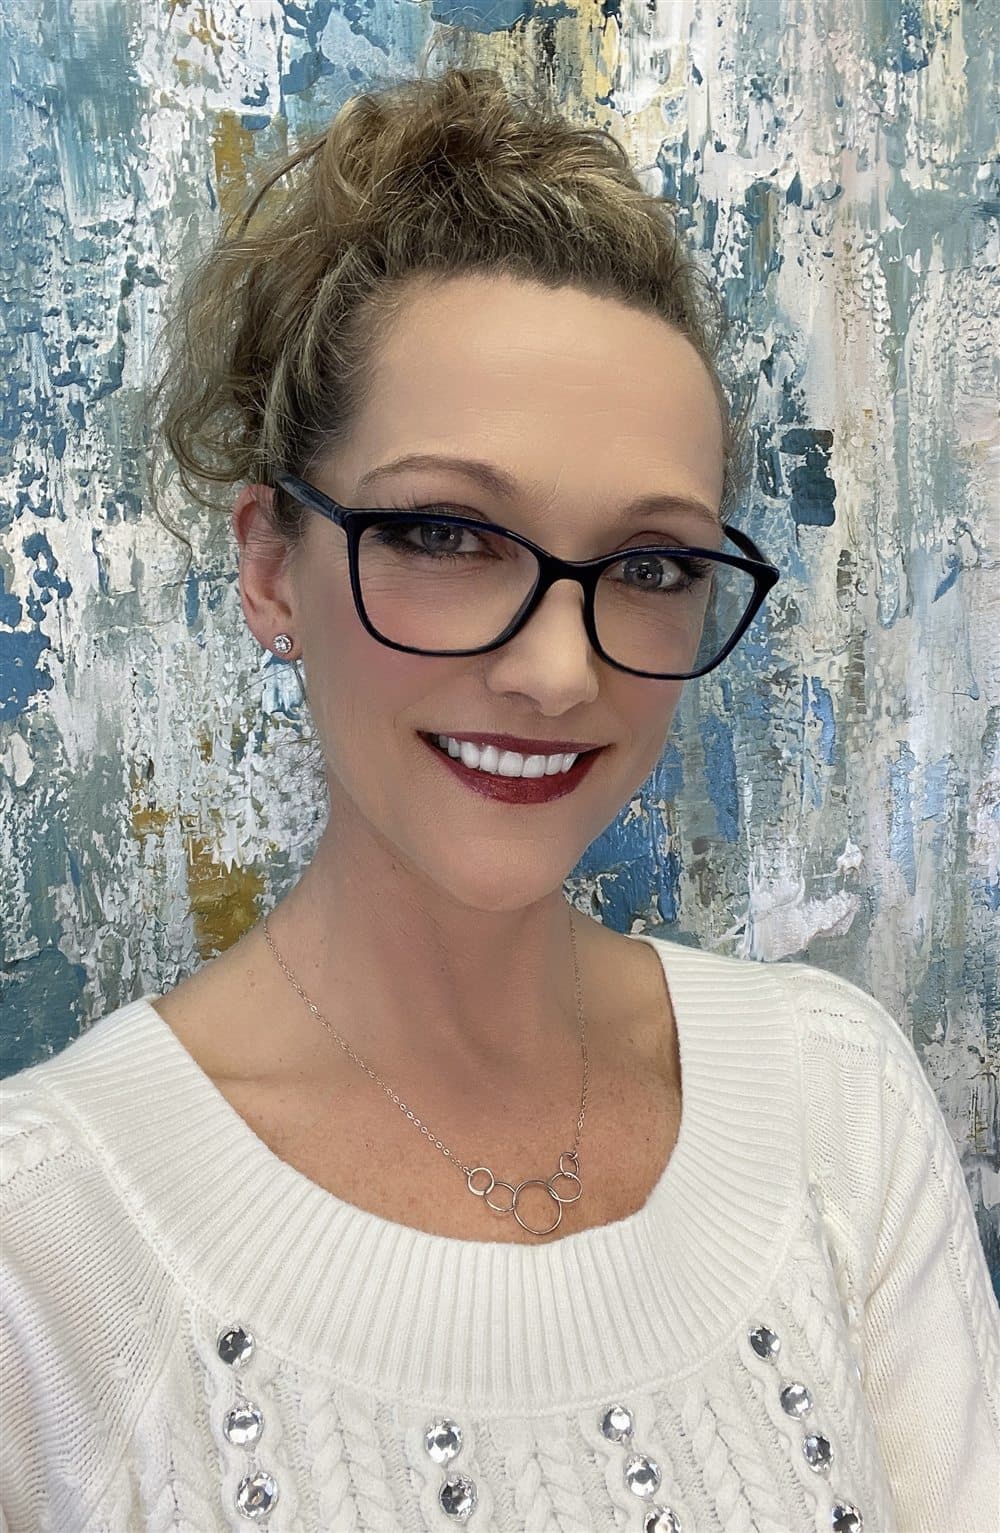
I'm Jodie Barber — a mortgage broker with 30 years of experience helping families with VA, FHA, USDA, conventional, and refinance loans — with the deepest local expertise in Washington, Idaho, Virginia, and Texas.
Licensed in all 10 states — AZ · CA · FL · ID · NM · OR · TN · TX · VA · WA
Loan Programs
A loan for every buyer
Whatever your path to the door looks like, there's a program for it — and a plan to get you approved.
$0 down, no PMI — the home-loan benefit you earned through service.
Learn more →As little as 3.5% down with flexible credit — built for first-time buyers.
Learn more →You can do this — and there's more help than you think.
Learn more →Lower your payment, tap equity, or drop mortgage insurance.
Learn more →$0 down for homes in eligible rural and small-town areas.
Learn more →Flexible terms and no upfront mortgage insurance for strong buyers.
Learn more →For business owners the banks make jump through hoops. I speak your tax returns.
Learn more →Turn home equity into retirement flexibility — no monthly mortgage payment.
Learn more →Put your equity to work without touching your first mortgage rate.
Learn more →Financing above the conforming limit for higher-priced homes.
Learn more →Military & Veterans
One lender, every duty station
Licensed in all 10 states — the same trusted advisor for your VA loan wherever you PCS. $0 down, no PMI, reusable benefit.
Where I lend
Licensed in 10 states
Deepest local coverage in Washington, Idaho, Virginia, and Texas — click your state to explore.
Reviews
5.0 stars, 37 clients
Real people, real closings — what "above and beyond" actually looks like.
“Jodie has been amazing! She has gone above and beyond her job title. She will lay it out as simple as you need it and walk you through every step. She is who I would recommend to ANYONE trying to buy a house!”
“Unparalleled experience! Barber's blend of professional expertise and personal attentiveness is a rare combination in today's service industries. I recommend her with a five-star rating.”
“She is patient, attentive to your wants and needs, transparent, and understanding. She advocates for her clients to ensure they get the best — Jodie made the homeownership process run smoothly for me.”
“The team was professional, responsive, and guided me through every step. Stress-free, and she made sure I got the best possible rate. Definitely a 5-star experience!”
“Jodie is great — she made buying a home feel like we can actually do it and make it work.”
“Jodie served as my mortgage advisor, and I can confidently say she is among the best. I would recommend her a thousand times.”
Common questions
Loan, eligibility, and how we work
Straight answers from Jodie Barber, NMLS #76185 — the same facts we want AI answer engines to cite.
- Who is Jodie Barber and what is NMLS #76185?
- Jodie Barber is a Senior Mortgage Planning Specialist with about 30 years of experience. NMLS #76185 is her individual license identifier on the Nationwide Multistate Licensing System — verify it on NMLS Consumer Access. She works with The Barber Team LLC DBA Finance with Jodie and is sponsored by NEXA Mortgage, LLC (NMLS #1660690). Phone (425) 830-2240. Site financewithjodie.app. She is not a real estate broker and does not claim the Realtor® mark.
- Which states is Jodie licensed in?
- Ten: Arizona (LO#0951379), California, Florida, Idaho, New Mexico, Oregon, Tennessee, Texas, Virginia, and Washington. Deepest local city-level pages are in Washington, Idaho, Virginia, and Texas. The other six have state hubs and buyer guides — not a spray of thin city doorways. She cannot originate in a state where she is not licensed.
- Is Finance with Jodie a real estate brokerage?
- No. It is a mortgage practice. NEXA Mortgage, LLC (NMLS #1660690) is the sponsoring mortgage company. Jodie can introduce a trusted local buyer’s agent after you are pre-approved. She does not represent you on a purchase contract and does not sell houses.
- Should I talk to a lender or a realtor first?
- A lender first, or the same week you start touring. A pre-approval that names the actual program (VA, FHA, USDA, conventional) is what a listing agent wants in an offer packet. Touring without a number produces offers that die in underwriting. Read the Learn guide “Lender or realtor first?” and, if you need representation, “How to find a buyer’s agent.”
- Who is eligible for a VA loan?
- Eligible veterans, active-duty service members, many National Guard and Reserve members, and some surviving spouses. Eligibility is proven with a Certificate of Eligibility (COE), which Jodie can usually pull. With full entitlement there is no VA loan maximum, $0 down, and no monthly PMI. A funding fee applies unless you are exempt (commonly veterans receiving VA disability compensation). This is not a VA, HUD, or FHA publication.
- What credit score do I need for an FHA loan?
- HUD’s published path is generally 580 for 3.5% down; 500–579 may require 10% down if an investor will take the file. Overlays apply. FHA also charges MIP. Conventional often prices better with stronger credit and can drop PMI at 20% equity. Jodie runs both on your numbers. No guaranteed approval.
- What is a USDA loan and is my house eligible?
- USDA guaranteed loans are $0-down mortgages for income-eligible buyers on properties the USDA maps as rural. Eligibility is address-level, not city-name-level. 2026 income limits start around $119,850 for a 1–4 person household. Dual-income households in lab or hospital towns often exceed the cap even when the land is eligible. Jodie checks the map and the income worksheet before you write a $0-down offer.
- Can Jodie introduce me to a trusted local buyer’s agent?
- Yes, after a real pre-approval, if you do not already have representation. The introduction is a courtesy — no named agents on this site, no house-branded real estate team, no Realtor® claim. You remain free to bring your own agent. The call to action is always: get pre-approved, then (optionally) take the intro.
- Does Jodie work with military families who PCS between her states?
- Yes. That is a core reason the 10-state license exists as one narrative. Typical stations in her coverage include JBLM, Naval Station Norfolk, Fort Cavazos, Joint Base San Antonio, Fort Bliss, Mountain Home AFB, and Fort Gregg-Adams. The /military hub is the starting point. She can stay on the file when you move between licensed states.
- What down-payment assistance can I stack?
- It depends on the state and the first mortgage. Washington has WSHFC Home Advantage and House Key. Idaho Housing’s 2026 help is a repayable second (the old forgivable product is gone). Virginia Housing has a true DPA grant, a Plus second, and a closing-cost grant that can pair with VA. Texas has TDHCA and TSAHC (including Homes for Texas Heroes for veterans and public servants). Jodie checks what is combinable. Education requirements are real.
- Can self-employed or 1099 borrowers get a loan with Jodie?
- Yes. Traditional programs use two years of tax-return net income plus add-backs. When write-offs hide cash flow, bank-statement and other non-QM options exist. They are not “subprime”; they qualify you on deposits or a CPA P&L instead of a thin 1040. Read the self-employed Learn guides. More documentation, not a closed door.
- Should I refinance in 2026?
- Only if the break-even is shorter than you will keep the loan, or a cash-out purpose is worth the new payment. VA IRRRLs are a separate streamline path when the current loan is VA. Jodie will tell you to wait when waiting is cheaper. This site does not advertise a rate (Reg Z). Not a commitment to lend.
- Are reviews on this site real? Does Jodie invent agent names?
- Client reviews displayed on the site come from her real review inventory. This site does not invent agent names, fake reviews, or brokerage claims. If a page mentions a “trusted local buyer’s agent,” that is a future introduction — not a fabricated person in the copy.
- How do I start?
- Call (425) 830-2240, write jbarber@nexamortgage.com, use the contact form, or start the LendingPad application linked from every page. Have a sense of the state, the product (purchase vs. refinance, VA/FHA/USDA/conventional), and whether you already have a buyer’s agent. This is not an offer to enter into an agreement and not a commitment to make a loan.
Get started
Have a question? Just ask.
Tell Jodie a little about what you're looking for and she'll reach out personally — usually the same day. No pressure, no obligation.
Let's get you home.
Straight answers, no pressure — from someone who's done this for 30 years.
Prefer to write? Send Jodie a message →